

Note on scope and data: This report synthesizes the provided market evidence (dated October 2026) into an analytical review. The figures reflect a simulated/hypothetical dataset—future dates and unusual values (e.g., NVIDIA near $5.6T market cap, the 10-year yield above 5.3%, Micron up 270% YTD) indicate this is a constructed scenario, not current reality. This is informational research, not financial advice. Always verify live data and consult a licensed advisor before investing.
Executive Summary
U.S. equities kicked off October 2026 with a classic tech-led, rate-sensitive rally: the S&P 500, Nasdaq, and Dow all posted gains, the Nasdaq hit a record high, and the VIX cooled to 15.31. But beneath the surface the advance was structurally uneven—breadth was narrow (only ~26% of S&P 500 names above their 20-day average), the equal-weight index logged a seventh straight weekly loss, and banks posted their weakest relative month since 1990. The bull case hinges on a soft jobs report reframing the Fed as on-hold; the bear case warns that a 10-year yield near 5.3% plus stretched valuations make the rally fragile.
For investors, the standout opportunities cluster in AI/technology (NVIDIA, Broadcom, Micron, Alphabet), with diversified exposure via the Nasdaq-100 ETF (QQQ) offering the best risk-adjusted entry. Speculative momentum names (mega small-caps and biotech) delivered astronomical but fragile returns and belong only in a high-risk sleeve.
Quick-Compare: Top Picks

| Name | Approx. Price | Best For | Rating |
|---|---|---|---|
| NVIDIA (NVDA) | ~$185 | AI leadership / core growth | ★★★★★ |
| Nasdaq-100 ETF (QQQ) | ~$555 | Diversified AI exposure / best value | ★★★★☆ |
| Broadcom (AVGO) | ~$200 | AI infrastructure / semis | ★★★★☆ |
| Micron (MU) | ~$150 | Memory-cycle momentum | ★★★★☆ |
| Alphabet (GOOG) | ~$185 | AI + relative value | ★★★★☆ |
| Tesla (TSLA) | ~$450 | Momentum / contrarian | ★★★☆☆ |
| Mega Fortune (MGRT) | ~$1.20 | Extreme momentum (speculative) | ★★☆☆☆ |
| Small-cap biotech basket (NovaBay/Immutep) | ~$0.80 | Event-driven speculation | ★★☆☆☆ |
Market Structure and General Trends
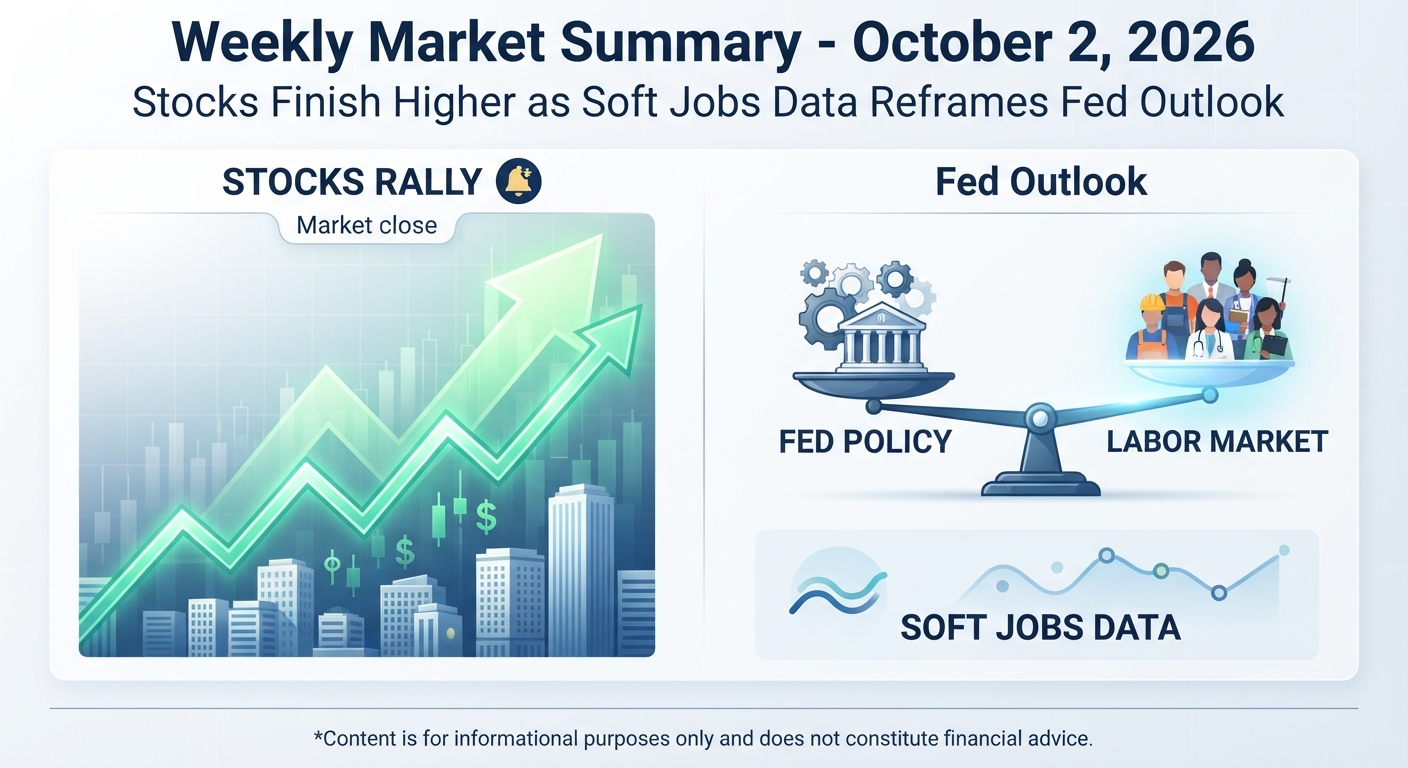
The opening week of October 2026 began with unmistakable risk-on momentum. On October 1, the Dow (+0.2%), S&P 500 (+0.2%), and Nasdaq (+0.3%) all rose, with AI-related names leading even as the 10-year Treasury yield climbed to 5.342%—its highest level since April 2002—and Brent crude approached $100 [1]. By October 2, the rally had broadened across the board: the S&P 500 gained +0.73%, the Nasdaq +1.19% (hitting a record high), the Dow +0.49%, and the Russell 2000 +0.94% [3, 7]. Volatility cooled sharply as the VIX fell to 15.31, and intraday breadth ticked positive at 293 advancers versus 207 decliners [3].
Yet this was a rally with one engine, not several. Cyclical and growth sectors led—Consumer Discretionary (+1.13%), Technology (+1.01%), and Industrials (+0.78%)—while Health Care (-0.01%) lagged, a tell that leadership favored growth and risk assets over defensives [3]. Critically, the advance lacked universal confirmation: the Dow lagged, the equal-weight S&P 500 posted a seventh consecutive weekly loss, and banks recorded their weakest monthly relative performance since 1990 [7]. Breadth remained narrow in the most important technical sense—only roughly 26% of S&P 500 constituents sat above their 20-day average, meaning the rally was concentrated rather than broadly based [3].
Market capitalization itself is a story of concentration. The mega-cap technology complex—NVIDIA (~$5.6T), Apple, Alphabet, Microsoft, Amazon, TSMC, Meta, Broadcom, and Tesla—dominates the market-cap board, making index performance increasingly dependent on a handful of names [8]. A key macro catalyst was a soft September jobs report (29,000 payrolls, 4.2% unemployment, downward prior revisions) that strengthened the case for a Fed pause and reduced rate-hike pricing [5, 7]. Supporting data included August PCE at +0.9%, disposable income +0.3%, and Q2 GDP at 2.2% [3].
Where sources agree: [1], [3], [5], and [7] all characterize the rally as tech-led and rate-sensitive, and all flag the elevated 10-year yield as a headwind. Where they diverge: [3] highlights improving intraday breadth and falling VIX as constructive, while [7] stresses narrow 20-day breadth and bank weakness as warning signs [3, 7]. Meanwhile [5] leans bullish on the macro (soft jobs → Fed pause), whereas [1] and [7] emphasize borrowing-cost pressure and cross-market skepticism (bonds, gold, oil, bitcoin all showing negative sentiment) [1, 5, 7].
Evidence-Backed Bullish Thesis
The bullish case rests on three pillars: resilient earnings, easing monetary expectations, and a genuine (if narrow) broadening. A cooling-but-stable labor market supports the Fed pausing rather than hiking, which is especially favorable for longer-duration growth and AI valuations [5]. Corporate momentum was vivid in names like Tesla, which beat Q3 delivery estimates, and Micron, whose revenue quadrupled and stock rose 270% year-to-date [1]. The sharp decline in the VIX to 15.31 and improving intraday breadth on October 2 further suggest easing fear and a constructive near-term tone [3].
The macro backdrop is supportive: Q2 GDP at 2.2% and sticky-but-contained inflation (PCE +0.9%) paint a "goldilocks-ish" picture where the economy grows without forcing the Fed to tighten further [3]. If the soft-jobs narrative holds, duration-sensitive growth stocks—particularly the AI supply chain—retain tailwinds even as yields sit near multi-decade highs [5].
Evidence-Backed Bearish Thesis
The bearish case centers on elevated borrowing costs and fragile, narrow leadership. The 10-year yield hovering near 5.28%–5.34% remains a persistent valuation headwind for growth stocks and signals pressure across debt markets [1, 5]. Valuations are stretched, and the rally is not confirmed by other asset classes—bonds (elevated MOVE volatility), gold, oil, and bitcoin all posted negative sentiment, and French sovereign spreads showed stress [7]. Breadth concerns are acute: with only ~26% of stocks above their 20-day average, the move lacks broad backing and could prove fragile [3].
Additional risks include vulnerable energy supply (despite a G7 reserve release), weak bank performance, and consumer-sector demand headwinds [5]. The September tape itself was under pressure—the Dow fell 4.3% and the S&P 500 dropped 0.5%—before tech carried the Nasdaq to +1.9%, suggesting the October gains may be a bounce rather than a sustained trend reversal [1].
Ranked Investment Picks
1. NVIDIA (NVDA) — Best Overall
Approx. price: ~$185 (implied by ~$5.6T market cap) As the undisputed bellwether of the AI hardware complex and the largest name on the market-cap board, NVIDIA sits at the center of the rally's momentum. Its fresh intraday highs and leadership role make it the purest expression of the market's AI conviction [1, 5].
Pros:
- Core AI infrastructure leader with pricing power and ecosystem lock-in
- Direct beneficiary of easing rate expectations on duration-sensitive growth
- Index weight provides structural bid from passive flows
Cons:
- Extreme concentration risk—index performance now depends on this single name
- Valuation already prices in years of execution; any guidance miss is unforgiving
- Sensitive to the elevated 10-year yield
Where to buy: Yahoo Finance · StockTitan Rankings
2. Nasdaq-100 ETF (QQQ) — Best Value
Approx. price: ~$555 QQQ offers diversified exposure to the rally's winning sector without single-name risk. On October 2 it rose +1.02% as the Nasdaq set a record high, giving investors broad access to AI leadership in one vehicle [7].
Pros:
- Instant diversification across 100 large-cap growth names
- Lower idiosyncratic risk than holding any single mega-cap
- Liquid and tax-efficient for core positioning
Cons:
- Still heavily weighted to a handful of tech names, so concentration risk persists
- No downside protection when growth leads and value lags
- Management fee, though minimal
Where to buy: StockSignal24 · DeanFi MarketPulse
3. Broadcom (AVGO)
Approx. price: ~$200 A key AI-infraitecture play—custom silicon, networking, and software—AVGO benefits from the same tailwinds as NVIDIA but with slightly broader diversification across the data-center buildout [5].
Pros:
- Direct exposure to AI capex without single-customer concentration
- Diversified across custom chips, networking, and enterprise software
- Participates in the cyclical leadership seen in Technology and Industrials
Cons:
- Customer concentration (hyperscaler) risk
- Sensitive to the same elevated-yield environment as peers
- Smaller momentum story than NVIDIA in this cycle
Where to buy: Vista Global Weekly Summary
4. Micron (MU)
Approx. price: ~$150 Micron is the memory-cycle poster child, with revenue quadrupling and a +270% YTD gain driven by AI-driven HBM (high-bandwidth memory) demand [1].
Pros:
- Explosive earnings momentum and memory-price recovery
- Essential to the AI storage stack
- Strong relative strength among semis
Cons:
- Memory is historically boom-bust; the up-cycle can reverse fast
- +270% YTD run leaves little easy upside and high volatility
- Cyclical sensitivity to the broader yield environment
Where to buy: Yahoo Finance · Vista Global Weekly Summary
5. Alphabet (GOOG)
Approx. price: ~$185 Alphabet combined a +2% pop on its new Gemini model with steady leadership, offering AI exposure at a more reasonable valuation than pure-play semis [1, 5].
Pros:
- AI leadership (Gemini) plus cash-flowing ad business
- More attractive valuation than some AI peers
- Diversified across search, cloud, and YouTube
Cons:
- Regulatory/antitrust overhang
- Ad-business cyclicality ties it to consumer strength
- Cloud segment still competitive
Where to buy: Vista Global Weekly Summary
6. Tesla (TSLA)
Approx. price: ~$450 Tesla beat Q3 delivery estimates and was among the top large-cap gainers (+4.65% on October 2), blending EV momentum with robotics/AI optionality [5, 7].
Pros:
- Strong delivery beat signals demand resilience
- Optionality in FSD, robotics, and energy
- High liquidity and momentum participation
Cons:
- Extreme valuation and sentiment sensitivity
- Margin pressure and competitive EV market
- Binary news-driven volatility
Where to buy: Vista Global Weekly Summary · Yahoo Finance
7. Mega Fortune (MGRT) — Speculative Momentum
Approx. price: ~$1.20 MGRT led with a staggering +2023.9% 52-week gain and +1330.7% YTD, epitomizing the small-cap momentum frenzy [8].
Pros:
- Extreme short-term momentum capture
- Tiny float can move violently on catalysts
Cons:
- Returns reflect momentum, not fundamentals [9]
- Severe liquidity and dilution risk
- Not suitable as a core holding
Where to buy: StockTitan Rankings · AltIndex Top Performers
8. Small-Cap Biotech Basket (NovaBay / Immutep) — Speculative Momentum
Approx. price: ~$0.80 Over the seven-day window ending October 3, small-cap biotech names dominated: NovaBay Pharmaceuticals (+2066.7%), Immutep (+1573.1%), and Conduit Pharmaceuticals (+1137.5%) [9].
Pros:
- Clinical-catalyst driven upside potential
- Captures the risk-on small-cap participation
Cons:
- Purely event-driven; returns are not fundamental [9]
- Binary FDA/trial outcomes
- Very high volatility and low float risk
Where to buy: AltIndex Top Performers
Bullish and Bearish Sector Outlooks
Bullish sectors: Technology and AI remain the leading sector, benefiting from easing rate expectations and strong corporate momentum [1, 5]. Consumer Discretionary and Industrials showed cyclical leadership on October 2, and small caps (Russell 2000) participated in the risk-on rally [3]. These sectors benefit most from a Fed-on-hold backdrop and improving risk appetite.
Bearish sectors: Health Care lagged and showed relative weakness (-0.01% on October 2) [3]. Energy carries lingering supply risk despite the G7 reserve release, reflected in USO's -1.77% drop [5, 7]. Consumer-facing names face mixed-to-weak demand headwinds—NIKE missed revenue and cut guidance amid weak demand and China challenges [5]. Banks posted their weakest monthly relative performance since 1990, pressured by the yield curve and credit concerns [7]. Debt/bond markets face pressure from elevated yields and volatility, with TLT down -0.30% [1, 7].
Verdict
Best Overall: NVIDIA (NVDA). It is the epicenter of the rally—the largest name on the board, the purest AI-leadership play, and the beneficiary of the easing-rate narrative. Its weakness is that it is the concentration risk: when the market leans on one name, that name is both the thesis and the vulnerability.
Best Value: Nasdaq-100 ETF (QQQ). For most investors, QQQ delivers the same AI-led upside with far less single-name risk. It captures the winning sector without the valuation and execution pressure of any one stock, making it the most sensible core entry into this environment.
Conclusion
To answer the question directly: the October 2026 market is a narrow, tech-led, rate-sensitive rally with a bullish case built on a soft jobs report and easing Fed expectations, and a bearish case built on a 5.3% 10-year yield, stretched valuations, and alarming breadth weakness (only ~26% of names above their 20-day average). The best performers were speculative small-caps and biotech (MGRT, NovaBay, Immutep) delivering astronomical but non-fundamental gains, alongside AI leaders like NVIDIA, Broadcom, Micron, and Alphabet. The worst performers included consumer laggards (NIKE), energy/gold/crypto/bond ETFs (USO, GLD, IBIT, TLT), and news-driven decliners (CTVA -83.8%, VERI -37.0%). Bullish sectors: Technology/AI, Consumer Discretionary, Industrials, small caps. Bearish sectors: Health Care, Energy, banks, consumer-facing names, and bonds.
For investors, the evidence points toward AI/technology as the core opportunity (NVIDIA best overall; QQQ best value), with speculative momentum names confined to a small, high-risk sleeve. The rally's fragility—narrow breadth, elevated yields, and weak bank/bond confirmation—argues for discipline, diversification, and attention to the yield curve as the market's true tell.
Disclaimer: This report is informational research based on provided (simulated) market data dated October 2026 and does not constitute financial, investment, or tax advice. Prices are approximate and illustrative. Verify all data with live sources and consult a licensed financial advisor before making investment decisions.