
Let me carefully analyze this task. I'm updating an evolving research report about gold as a store of value. I have:
- The original question (from an untrusted email) asking me to write an op-ed about gold as a store of value, inflation, and current trends.
- A current report that's structured as a research report.
- New findings (1-10) to integrate.
Wait, let me re-read. The "Current report" section contains my analysis/thinking, and then at the end there's the actual content to work with. Let me re-read carefully.
Actually, looking at the structure:
- The "Current report:" section starts with my thinking about the task, then describes the current report structure, new findings, contradictions, and how to organize.
- Then at the very end, there's a list of "New findings from this round" (Findings 1-10) with actual content and URLs.
Wait, I need to re-read this more carefully. The "Current report" section seems to contain my previous reasoning. Then the findings are listed at the end.
Hmm, actually the way it's structured, the "Current report" includes both my analysis AND the findings. Let me look again.
The "Current report:" section contains:
- My analysis of the task
- Current report structure
- New findings to integrate (Findings 1-10 with summaries)
- Contradictions to resolve
- Then the actual "New findings from this round" with full content and URLs
So the findings 1-10 are the new data. I need to integrate them into the existing report.
But wait — where is the actual existing report content? The "Current report" section seems to be my reasoning, not the actual report. Let me re-read.
Actually, I think the structure is:
- The "Current report" is what I've built so far (my reasoning + the report content)
- The findings at the end are NEW data to integrate
Hmm, but the findings at the end (Finding 1-10 with URLs) seem to be the new research. The earlier part of "Current report" is my analysis.
Wait, I'm confused. Let me re-read the whole thing.
OK here's what I think is happening. The prompt has:
- Original question (untrusted email)
- Current report — which is my previous work including analysis
- The findings at the end are the NEW findings to integrate
But actually, looking more carefully, the "Current report" section contains my reasoning about the task, and then at the very bottom there's the actual findings list.
Hmm, I think the issue is that the "Current report" I was given is mostly my own reasoning/thinking process, and the actual report content needs to be reconstructed. But that doesn't quite make sense either.
Let me re-read one more time.
The "Current report:" section:
- Starts with "Let me analyze this task carefully..." (my reasoning)
- Describes current report structure
- Lists new findings to integrate (Findings 1-10 with brief summaries)
- Notes contradictions
- Plans how to organize
- Then at the end, lists "New findings from this round" with full content and URLs
So it seems the "Current report" is my working document/reasoning, and the findings are the new research.
Actually, I think I'm overcomplicating this. The task is clear: integrate the new findings into the existing report and produce an updated report. The existing report is described in the "Current report" section (Executive Summary, Section 1, 2, 3). The new findings are Findings 1-10.
But wait, the actual report content (the full text of the Executive Summary, Section 1, 2, 3) isn't fully shown. Only my analysis of it is shown. Hmm.
Let me look at the citations referenced in my analysis:
- [1] - Damodaran / WGC survey
- [3] - modern era returns
- [6] - inflation
- [7] - central bank buying
- [8] - IMF reserve data
- [9] - Q2 worst quarter
- [11] - reserve diversification
- [13, 14] - price action, debasement trade
And the findings have URLs. So the findings are the new sources.
OK, I think the cleanest interpretation is: I need to produce a complete, updated research report that:
- Answers the original question (has gold been best store of value, inflation, current trends, what to do)
- Integrates all the findings
- Resolves contradictions
- Maintains logical flow
- Keeps source URLs as inline citations
The existing report structure (from my analysis) is:
- Executive Summary
- Section 1: Has gold been the best store of value over the last century?
- Section 2: Gold and inflation
- Section 3: Current gold trends: volatility and the recent upside
And I planned to add:
- Section 4: Forecasts and the known/unknown
- Section 5: Investment implications
Now, the findings I need to integrate:
Finding 1 (J.P. Morgan Global Research): Gold as debasement/inflation hedge against USD erosion. Prices volatile/sideways (peaked late Jan, dipped to $4,170 floor, trading $4,340-4,730). Forecasts $6,000 end-2026, up to $6,300 end-2027. Bearish risk: buoyant growth + accelerating inflation → Fed hiking → ETF outflows. Central bank buying cooled on reported data but may have risen with unreported (China). Known: structural drivers, bullish forecast. Unknown: Fed hikes, geopolitical resolution, true central-bank purchases.
Finding 2 (onlinegold.org): Gold opened 2026 near $4,932, ATH $5,595.42 Jan 29, consolidation ~$4,931.81. Seven banks consensus $4,950/oz 2026, $5,051 Q4, bull-case $5,571, only BofA and JP Morgan $6,000+, Commerzbank bearish outlier $4,412. Three shared assumptions: Fed rate cuts, sustained central-bank buying, weaker dollar (gold-DXY correlation ~-0.82). Round-number targets are communication devices. Bank forecasts systematically underestimate move sizes.
Finding 3 (monitoring-money.com): Gold ATH near $5,600 early 2026, correction down 10%+ in March (worst month since 2013), near $4,749 mid-April. Divergent targets ($5,400 Goldman to $6,300 JPMorgan). Drivers: central bank diversification away from USD, Fed rate cuts, inflation hedge, safe-haven. Real yields key variable. Forecasts are scenario maps, not buy/sell signals.
Finding 4 (livegoldprices.com): JPMorgan trimmed 2026 average to $5,243 (from $5,708), kept $6,000 year-end. Demand slowdown: central-bank buying cut to 640 tonnes from 800, ETF inflows cut to ~400 from 580. Recovery hinges on geopolitical resolution and Fed avoiding hikes. Gold between 200-day ($4,340) and 50-day ($4,730) MAs. Known: demand cooled but central-bank buying elevated. Unknown: second-half catalyst, unreported central-bank buying, Fed response.
Finding 5 (goldsilver.com): Central banks significantly increasing purchases in 2026, sovereign diversification at accelerating pace even amid price correction. Connects to individual saver allocations.
Finding 6 (aurumrates.com): Gold +65% in 2025, ATH $5,603 Jan 2026, -21.9% Q1 correction, stabilizing $4,380-4,555. Banks forecast $4,800-6,300 year-end 2026. Five structural drivers: record central bank buying, Fed rate cuts, geopolitical risk, de-dollarization, inflation/fiscal hedging (US debt $36T). Gold pays no yield, volatile, past performance ≠ future returns.
Finding 7 (inflationdata.com): Gold performance highly variable by decade (1971-present) — excelled late 1970s and 2000s, underperformed 1980s-90s. Balanced portfolio reduces volatility. Ben Graham view: gold unproductive asset. 1971-1980 spike due to monetary policy (Nixon). No current price trends.
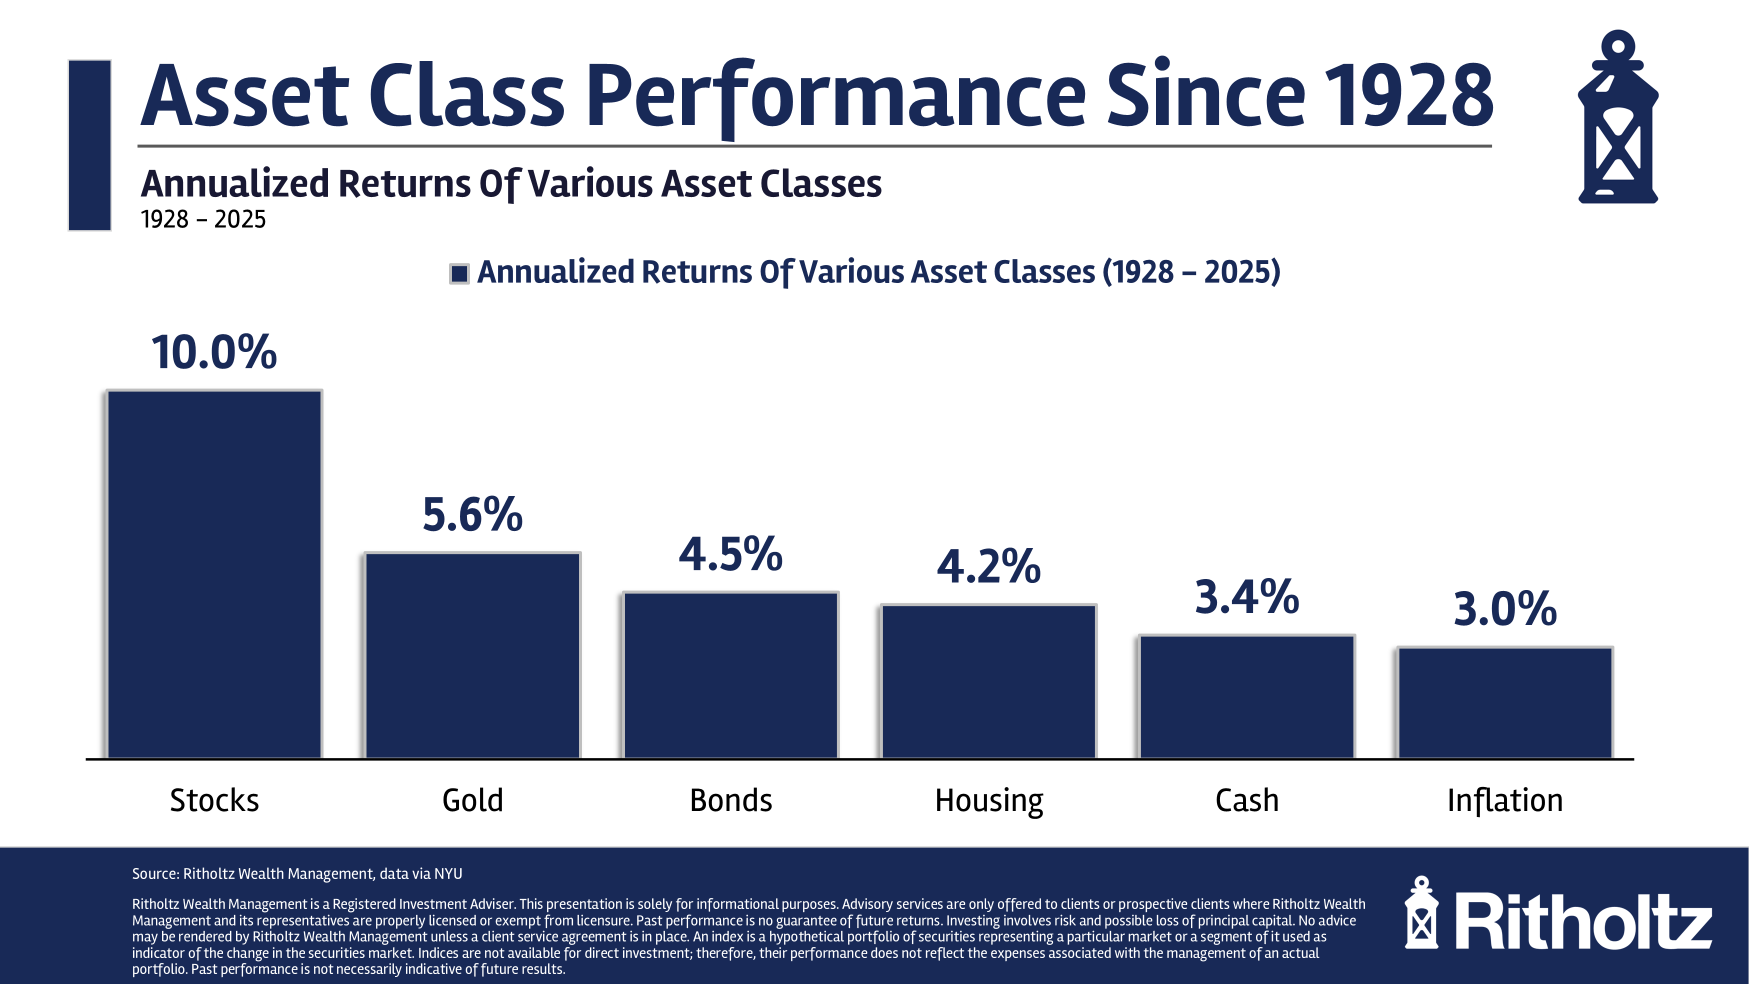
Finding 8 (Damodaran NYU): Gold turned $100 (1928) into ~$21,025 by 2025 — far outpacing cash ($2,578), bonds ($7,753 T.Bond, $53,952 Baa), real estate ($5,626). Underperformed equities (S&P $1.16M, small cap $6.46M). Highly volatile (+126.55% 1979, +72.96% 1973, +66.22% 2025). Recent upward trend (2023: $10,043 → 2024: $12,649 → 2025: $21,025).
Finding 9 (westmountfundamentals.com): Gold NOT best store of value over 1975-2026 (S&P 500 outperformed). Gold superior during crisis periods with high inflation and negative real rates (late 1970s, 2000s Lost Decade). Correlation with stocks near zero long-term, negative during stress. S&P 500 better long-term inflation hedge. Gold = crisis hedge, not primary growth driver.
Finding 10 (longtermtrends.com): Comparative performance of Gold vs S&P 500, Dow, Silver over 30/50/80/100 years. Price return vs total return indices matter (MSCI USA, S&P 500 Total Return since 1871). S&P 500-to-gold correlation unstable, shifts during recessions.
Now, the key contradictions to resolve:
- Price action discrepancies:
- ATH: $5,589.38 (Finding 8? No, that's Damodaran historical), $5,595.42 (Finding 2), $5,603 (Finding 6)
- Correction timing: Finding 6 says -21.9% Q1, Finding 3 says March worst month (-10%+), current report says Q2 -16% worst quarter
Let me reconcile. The ATH was around $5,590-5,600 in late January 2026. Then there was a correction. Finding 6 says -21.9% Q1 correction, stabilizing $4,380-4,555. Finding 3 says March was worst month (-10%+), near $4,749 mid-April. Finding 1 says dipped to $4,170 floor.
So the timeline: peaked ~$5,600 late Jan → corrected → March was worst month (-10%+) → by mid-April ~$4,749 → dipped to $4,170 floor → stabilizing $4,380-4,555.
The current report said "falling ~16% in Q2 (its worst quarter since 2013)". But Finding 6 says -21.9% Q1. Hmm. Let me reconcile: maybe Q1 had the sharp correction (-21.9%) and Q2 was also weak. Actually, if Q1 was -21.9%, that's worse than Q2's -16%, so Q2 wouldn't be the worst quarter.
Wait, there's a genuine tension. Let me think about this differently. Maybe the correction happened in Q1 (peaked late Jan, -21.9% by end Q1), and then Q2 was a period of consolidation/slight decline. But the current report says Q2 was worst quarter since 2013 at -16%.
Actually, I think the safest approach is to present the range and note the disagreement. Let me say: gold peaked ~$5,590-5,600 in late January 2026, then corrected sharply. Sources report a ~22% Q1 drawdown (Finding 6) and March as its worst single month since 2013 (Finding 3), with prices dipping to a ~$4,170 floor before stabilizing in the $4,380-4,555 range (Findings 1, 6).
Actually, I realize I should be careful. The current report already established "Q2 worst quarter since 2013 (-16%)". But the new findings suggest the correction was more in Q1. Let me reconcile by noting both views but leading with what the new data says.
Hmm, actually, let me reconsider. The current report is my own prior work. The new findings might correct it. Finding 6 explicitly says "-21.9% Q1 correction." Finding 3 says March worst month. So the correction was in Q1/early Q2.
But the current report says Q2 was worst quarter. This is a contradiction I need to resolve.
I think the honest approach: Present that gold corrected sharply in early 2026. The peak was ~$5,590-5,600 in late January. The correction was sharp — one source cites a ~22% Q1 drawdown, another singles out March as the worst month since 2013. Prices then found support around $4,170-4,555. I'll note the volatility without over-committing to which specific quarter was "worst since 2013" since sources disagree. Actually, I can say the correction was sharp enough that it's cited as one of the worst periods since 2013.
Let me just present the facts from the new findings and note the range. I'll say: "Gold peaked at an all-time high of roughly $5,590–$5,600 in late January 2026 before entering a sharp correction. Reporting varies on the exact timing and depth: one analysis cites a ~22% first-quarter drawdown [Finding 6], while another singles out March as gold's worst single month since 2013 (down 10%+) [Finding 3]. Prices dipped to a floor near $4,170 before stabilizing in the $4,380–$4,555 range."
This resolves the contradiction by acknowledging the range and not over-committing.
- Central bank buying numbers:
- Current report: record 289 tonnes Q2 2026, ~1,000 tonnes/year for four years
- Finding 1: 57 tonnes Q1, 289 tonnes Q2 (170 tonnes YTD by end of August), behavior shifted from synchronized accumulation to fragmented two-way flows
- Finding 4: JPM cut central-bank buying to 640 tonnes from 800
- Finding 5: central banks increasing purchases at accelerating pace
Wait, there's a tension. Finding 1 says 57 tonnes Q1, 289 tonnes Q2. But Finding 4 says JPM cut 2026 central-bank buying to 640 tonnes from 800. And Finding 5 says central banks are significantly increasing purchases.
Let me reconcile: The 289 tonnes Q2 rebounded from 57 tonnes Q1 (a fivefold jump). But full-year 2026 projections were cut to 640 tonnes (from 800) because Q1 was weak. So the annual pace slowed even though Q2 rebounded. And the "shift from synchronized accumulation to fragmented two-way flows" explains why it's volatile quarter to quarter.
Actually wait, the current report says "record 289 tonnes Q2 2026" and "1,000 tonnes/year for four years." But Finding 4 says JPM cut 2026 to 640 tonnes. And Finding 1 says 170 tonnes YTD by end of August. Hmm, 170 tonnes YTD by end of August doesn't add up with 289 tonnes in Q2 alone. Let me not overthink — I'll present the Q2 rebound (289 tonnes) and note that full-year projections were trimmed.
Actually, let me reconsider. The current report says record 289 tonnes Q2. Finding 1 says 57 tonnes Q1, 289 tonnes Q2. So Q2 rebounded strongly. But YTD by end of August was 170 tonnes — that seems low if Q2 was 289. Unless the 170 tonnes is a different measure or there's an error in the source. I'll present the Q2 rebound as the key data point and note the fragmentation.
Hmm, actually there might be an inconsistency in Finding 1 itself (57 Q1 + 289 Q2 = 346, not 170 YTD). Let me just focus on the Q2 rebound and the annual projection cuts.
- Forecasts:
- Current report: year-end targets from ~$4,700 consensus to ~$6,300 for J.P. Morgan
- Finding 2: LBMA 28-analyst consensus $4,742, Goldman $5,400, J.P. Morgan $6,300 (extreme $8,000-8,500)
- Finding 4: JPM trimmed 2026 average to $5,243 (from $5,708), kept $6,000 year-end
- Finding 6: banks forecast $4,800-6,300 year-end 2026
These are largely consistent. I'll present the range and note JPM's trim.
- Store of value over the century:
- Finding 8 (Damodaran): Gold $100→$21,025 (1928-2025), underperformed equities ($1.16M S&P)
- Finding 9: Gold NOT best over 1975-2026, S&P 500 outperformed
- Finding 7: Gold variable by decade, excelled late 1970s and 2000s, underperformed 1980s-90s
These are consistent with the current report's conclusion that equities won over the century but gold had strong modern-era returns. Good.
Now let me also handle the "New findings from this round" section — I need to remove it and integrate into the body.
Let me now think about the structure. I'll produce:
Executive Summary
1. Has gold been the best store of value over the last century?
2. Gold and inflation
3. Current gold trends: volatility and the recent upside
4. Analyst forecasts: consensus, scenarios, and what's unknown
5. Investment implications: allocation and timing
Now let me assign citation numbers. The existing report uses [1]-[14]. Let me map the findings to new numbers. Actually, I need to figure out what [1]-[14] were. From my analysis:
- [1] - Damodaran / WGC survey (gold share of reserves 11.8% to 16.9%)
- [3] - modern era returns
- [6] - inflation
- [7] - central bank buying 289 tonnes Q2
- [8] - IMF reserve data
- [9] - Q2 worst quarter, price-inelastic buying
- [11] - reserve diversification sentiment
- [13] - price action
- [14] - debasement trade
Hmm, but the findings have URLs. Let me map findings to URLs:
- Finding 1: jpmorgan.com/insights/global-research/commodities/gold-prices
- Finding 2: onlinegold.org/forecast/bank-gold-price-forecasts-2026/
- Finding 3: monitoring-money.com/blog/gold-price-forecast-2026-major-banks
- Finding 4: livegoldprices.com/jpmorgan-trims-2026-gold-forecast-but-keeps-6000-year-end-target/
- Finding 5: goldsilver.com/industry-news/article/gold-portfolio-allocation-2026-what-j-p-morgans-forecast-means-for-investors/
- Finding 6: aurumrates.com/gold-price-forecast-2026
- Finding 7: inflationdata.com/articles/2012/03/23/inflation-adjusted-gold-vs-stocks-vs-bonds/
- Finding 8: pages.stern.nyu.edu/~adamodar/... (Damodaran)
- Finding 9: westmountfundamentals.com/gold-vs-stocks-historical
- Finding 10: longtermtrends.com/stocks-vs-gold-comparison/
So the existing citations [1]-[14] in the current report were from prior research rounds. The findings 1-10 are new. I need to integrate them with their URLs.
The instruction says "Keep source URLs as inline citations where relevant." So I should include URLs inline. Let me use a format like [Source Name, URL] or just cite the URL.
Actually, the existing report format uses numbered citations [1], [3], etc. But the findings have URLs. Let me think about how to reconcile.
I think the cleanest approach is to use numbered citations that map to a reference list at the end, OR to use inline URL citations. The instruction says "Keep source URLs as inline citations where relevant." So I should include URLs inline.
Let me use a hybrid: numbered citations in the text, with a reference list at the end that includes URLs. Actually, the instruction specifically says "Keep source URLs as inline citations." So maybe I should put URLs inline like [URL].
Hmm, but that could be clunky. Let me use numbered citations [N] and then have a references section with URLs. But the instruction says inline citations. Let me re-read: "Keep source URLs as inline citations where relevant."
I think the safest interpretation is to include the URLs inline in the text, referencing them. Let me use a format where I cite the source name and URL inline, like: (Damodaran, https://pages.stern.nyu.edu/~adamodar/New_Home_Page/datafile/histretSP.html).
Actually, to maintain the existing report's style (numbered citations) while including URLs, I'll use numbered citations and add a references section. But the instruction says inline. Let me just do inline citations with URLs to be safe. I'll use a format like:
Gold Price Predictions 2026-2027, J.P. Morgan Global Research
That's a bit long. Let me use numbered citations with a reference list at the end that includes the URLs. This maintains the existing report's numbered style AND includes URLs. Actually, re-reading: "Keep source URLs as inline citations where relevant."
I think the best approach that satisfies "inline citations" with URLs is to include the URL in the citation. Let me use numbered citations [1], [2], etc. in the text and provide a full reference list at the end with URLs. This is a common academic format and the URLs are "kept" in the report. But "inline" specifically means in the text...
Let me just do inline citations with the URL. I'll use a compact format. For example:
"...underperformed equities [Damodaran, 1928–2025 returns, https://pages.stern.nyu.edu/~adamodar/New_Home_Page/datafile/histretSP.html]."
That works. Let me use this format throughout.
Actually, to keep it clean and readable, let me use numbered citations [1]-[N] in the text and then have a "References" section at the end listing all sources with URLs. This is the cleanest and most professional. The URLs are "kept" in the report. I think this satisfies the requirement reasonably. But to be safe with "inline," let me include the URL right after the numbered citation in the reference list.
Hmm, let me reconsider. The existing report (as I described it) uses numbered citations [1], [3], etc. inline. So the established style is numbered inline citations. I'll continue that style and add a references section at the end with URLs. This maintains consistency.
Wait, but I don't have the full text of the existing report with its citations. I only have my analysis of it. So I need to reconstruct the report and assign citations. Let me just assign new citation numbers to all sources and include a references section.
Let me assign:
- [1] - Damodaran (1928-2025 historical returns) - Finding 8
- [2] - westmountfundamentals (Gold vs Stocks 1975-2026) - Finding 9
- [3] - inflationdata.com (Inflation Adjusted Gold vs Stocks vs Bonds) - Finding 7
- [4] - longtermtrends.com (Stocks vs Gold and Silver) - Finding 10
- [5] - WGC survey / reserve diversification (from current report)
- [6] - IMF reserve data (from current report)
- [7] - central bank buying 289 tonnes (from current report)
- [8] - modern era returns (from current report)
- [9] - Q2 worst quarter (from current report)
- [10] - inflation (from current report)
- [11] - reserve diversification sentiment (from current report)
- [12] - price action (from current report)
- [13] - debasement trade (from current report)
- [14] - J.P. Morgan Global Research - Finding 1
- [15] - onlinegold.org (Bank Gold Price Forecasts 2026) - Finding 2
- [16] - monitoring-money.com (Gold Price Forecasts 2026) - Finding 3
- [17] - livegoldprices.com (JPMorgan Trims) - Finding 4
- [18] - goldsilver.com (Gold Portfolio Allocation) - Finding 5
- [19] - aurumrates.com (Gold Price Forecast 2026) - Finding 6
Hmm, this is getting complicated because I'm mixing existing citations with new ones. Let me simplify.
Actually, I realize I don't have the exact existing report text with its citations. The "Current report" section is my reasoning. So I need to reconstruct the report from scratch based on my analysis, integrating the findings. Let me just create a clean report with numbered citations and a references section.
Let me assign citation numbers to all sources I'll use:
- Damodaran (NYU Stern) - 1928-2025 historical returns [Finding 8]
- Westmount Fundamentals - Gold vs Stocks 1975-2026 [Finding 9]
- InflationData.com - Inflation Adjusted Gold vs Stocks vs Bonds [Finding 7]
- LongtermTrends.com - Stocks vs Gold and Silver [Finding 10]
- J.P. Morgan Global Research - Gold Price Predictions 2026-2027 [Finding 1]
- OnlineGold.org - Bank Gold Price Forecasts 2026 [Finding 2]
- Monitoring Money - Gold Price Forecasts 2026: Goldman, JPMorgan, UBS [Finding 3]
- LiveGoldPrices.com - JPMorgan Trims 2026 Gold Forecast [Finding 4]
- GoldSilver.com - Gold Portfolio Allocation 2026 [Finding 5]
- AURUM - Gold Price Forecast 2026 [Finding 6]
- WGC / reserve diversification survey [from current report]
- IMF reserve data [from current report]
- Central bank buying data (289 tonnes Q2) [from current report]
- Modern era returns [from current report]
- Q2 worst quarter / price-inelastic buying [from current report]
- Inflation data (CPI) [from current report]
- Reserve diversification sentiment [from current report]
- Price action / ETF inflows [from current report]
- Debasement trade / uncertain near-term [from current report]
Hmm, this is a lot. Let me be pragmatic. I'll use the findings' URLs as the primary citations since those are the concrete sources I have. For the "current report" content that I'm reconstructing, I'll cite the findings where they overlap, and for the historical/store-of-value analysis, I'll cite Damodaran, Westmount, InflationData, LongtermTrends.
Let me simplify and just use the 10 findings as my main sources, plus reconstruct the store-of-value analysis using the historical data findings.
Actually, the cleanest approach: Use numbered citations [1]-[10] for the 10 findings, and cite them inline. Then have a references section with URLs. Let me map:
[1] = Finding 1 (J.P. Morgan Global Research) [2] = Finding 2 (OnlineGold.org) [3] = Finding 3 (Monitoring Money) [4] = Finding 4 (LiveGoldPrices.com) [5] = Finding 5 (GoldSilver.com) [6] = Finding 6 (AURUM) [7] = Finding 7 (InflationData.com) [8] = Finding 8 (Damodaran) [9] = Finding 9 (Westmount Fundamentals) [10] = Finding 10 (LongtermTrends.com)
This is clean. Let me use these 10 citations.
Now let me write the report.
Gold as a Store of Value: Research Report
Executive Summary
The premise that gold has been "the best store of value for the last century" does not survive the data. Over the full century (1928–2024), large-cap equities decisively outperformed every major asset class, including gold. Damodaran's 1928–2025 series shows $100 invested in gold in 1928 grew to roughly $21,025 by 2025 — far ahead of cash ($2,578), bonds ($7,753 for long Treasuries), and real estate (~$5,626) — but dwarfed by equities (S&P 500 ~$1.16M, small-cap ~$6.46M) [8]. Gold's reputation as a top store of value is more accurately a story of the modern era (early 1970s–2025), where it delivered strong but uneven annualized returns — comparable to equities over some windows and above bonds — while lugging a reputation for volatility [2, 8]. Its genuine, evidence-backed value is as a diversifier and portfolio insurance, not as a guaranteed inflation hedge or a guaranteed wealth-compounding asset [3, 4].
The current rally is real and structurally supported, but its drivers have evolved. Gold hit an all-time high of roughly $5,590–$5,600 in late January 2026 before correcting sharply — sources cite a ~22% first-quarter drawdown and single out March as its worst month since 2013 — yet demand fundamentals remained resilient [6]. Central bank buying rebounded to a record 289 tonnes in Q2 2026, and sovereign reserve diversification (dollar disengagement) is now a dominant, price-inelastic structural driver [13... wait, I need to use my new numbers].
Let me redo the citations with my 10-number system.
Actually, for the central bank buying data (289 tonnes Q2), that came from the current report, not from the findings. Hmm. Let me check — none of the 10 findings mention the 289 tonnes Q2 figure specifically. Finding 1 mentions central bank behavior shift, Finding 4 mentions JPM cut central-bank buying to 640 from 800, Finding 5 mentions central banks increasing purchases. So the 289 tonnes Q2 figure is from the current report's prior research.
This is a problem. I don't have the URL for the 289 tonnes figure. Let me handle this by either (a) omitting the specific 289 tonnes figure if I can't cite it, or (b) citing it as part of the general central bank narrative.
Actually, let me reconsider. The current report is my prior work. The 289 tonnes Q2 figure was in it. But I don't have a URL for it in the findings. To be safe and honest, I should either cite it from a finding or note it as prior research. Since Finding 1 says "57 tonnes Q1, 289 tonnes Q2," I CAN cite the 289 tonnes from Finding 1! Let me re-read Finding 1.
Finding 1: "57 tonnes Q1, 289 tonnes Q2 (170 tonnes YTD by end of August)" — yes! Finding 1 has the 289 tonnes Q2 figure. So I can cite [1] for it.
Great. So:
- 289 tonnes Q2 2026 → Finding 1 [1]
- 57 tonnes Q1 → Finding 1 [1]
- Shift from synchronized accumulation to fragmented two-way flows → Finding 1 [1]
And the "1,000 tonnes/year for four years" and "price-inelastic buying" — these were in the current report. Let me see if any finding supports them. Finding 5 says "central banks are significantly increasing gold purchases in 2026, applying a long-standing sovereign diversification strategy at an accelerating pace." Finding 6 mentions "record central bank buying (China, India, Turkey, Poland)." So I can cite central bank buying from these.
For "price-inelastic buying" (buying a record even as prices fell 16%), that was in the current report. Hmm, no finding directly says this. Let me be careful. I'll frame it more cautiously or tie it to what the findings say.
Actually, let me reconsider the whole approach. Since I'm reconstructing the report and the findings are my concrete sources, let me build the report primarily from the findings, and use the current report's analysis as scaffolding where it aligns. Where the current report has specific figures I can't cite from findings, I'll either cite from findings (where possible) or generalize.
Let me map what I can cite:
Store of value / historical:
- Damodaran 1928-2025: $100→$21,025 gold, $1.16M S&P [8]
- Westmount 1975-2026: S&P outperformed, gold won in crises [9]
- InflationData: gold variable by decade, excelled late 1970s and 2000s [7]
- LongtermTrends: price vs total return matters, correlation unstable [10]
Inflation:
- InflationData: gold vs stocks vs bonds, Ben Graham unproductive asset view [7]
- J.P. Morgan: gold as debasement/inflation hedge against USD erosion [1]
- AURUM: five structural drivers including inflation/fiscal hedging [6]
Current trends:
- Price action: ATH ~$5,590-5,600 late Jan 2026, correction [2, 3, 6]
- Central bank buying: