
Executive Summary
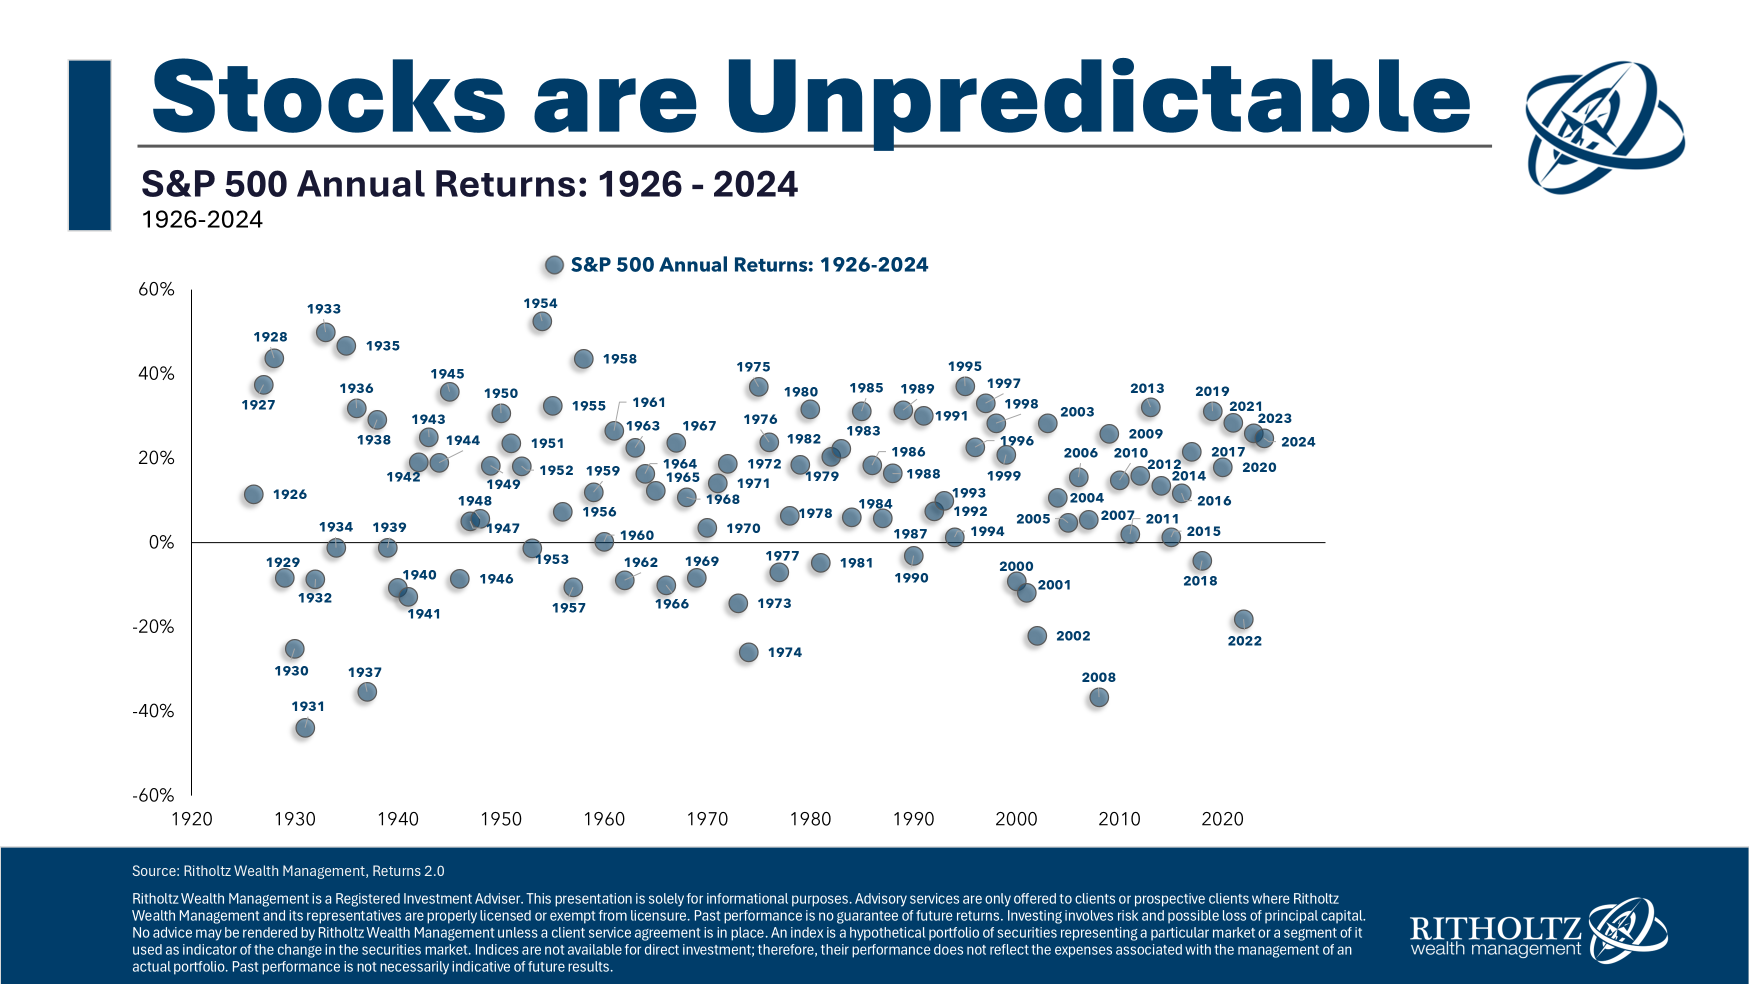
Gold's reputation as humanity's oldest and most reliable store of value is real—but it is routinely overstated, and the current euphoria deserves scrutiny. Over the full century (roughly 1928–2025), equities decisively crushed gold on total returns: stocks turned $1 into roughly $1,081 in inflation-adjusted terms, versus gold's meager ~$5.35. Gold did beat bonds, cash, and real estate and cleared historical inflation, but it significantly underperformed productive assets. Its reputation as a hedge is period-dependent—it excelled in the high-inflation 1970s and during the 2008 and COVID crises, but delivered double-digit annual returns in only 3 of the past 6 decades.
On inflation, the Fed's "not a big deal" framing has actually unraveled within its own projections: PCE estimates for 2026 were revised sharply upward (from 2.7% to 3.6%) in a matter of months, and the Fed hiked rates in September 2026 under Chair Kevin Warsh, who called inflation "too high and has been for too long." Today's gold rally is driven less by yields and more by a structural revolution in central-bank buying and geopolitical de-dollarization. For the everyday investor, the question is not "gold or nothing" but which vehicle best fits their goals—physical bullion for sovereignty, ETFs for efficiency, or miners for leverage. This report separates the data from the hype and ranks the practical ways to gain exposure.
The Headline Claim Doesn't Hold Up
The century-long comparison
The premise that gold has been "the best store of value for the last century" does not survive contact with the data. Over the full century, equities were the dominant long-run winner. Gold turned $1 into only about $5.35 in real (inflation-adjusted) terms over 100 years, versus roughly $1,081 for stocks investorsfriend.com/asset-performance/. The gap is staggering, and it reflects a structural divide: equities compound through earnings growth and reinvested dividends, while gold generates no cash flow, producing what amounts to "long flat real returns" punctuated by regime-specific spikes vieclaire.com/en/blog/best-performing-assets-of-the-last-century/.
That said, gold did earn its place as a legitimate store of value. Its nominal annual return from 1928–2024 was about +5.12%, comfortably beating bonds (+4.50%), cash (+3.31%), and real estate (+4.23%), and clearing the ~3% historical inflation rate for a real return of roughly +2.12% annually theprivateoffice.co.nz/blog/historical-returns-for-stocks-bonds-cash-real-estate-and-gold-ben-carlson. But it significantly underperformed stocks (+9.94%) and small caps (+11.74%) theprivateoffice.co.nz/blog/historical-returns-for-stocks-bonds-cash-real-estate-and-gold-ben-carlson. The honest conclusion: gold is a real, inflation-beating store of value, but it was not the century's best one—equities win on a total-return basis.
When gold actually earns its reputation
Gold's story is highly period-dependent. It kept pace with or outperformed the S&P 500 from 2001–2025 investorsfriend.com/asset-performance/, and during the high-inflation 1970s it surged roughly 500% in real buying power after Nixon ended the gold standard investorsfriend.com/asset-performance/. Its strongest performances cluster around currency distrust, the collapse of Bretton Woods, and negative real rates vieclaire.com/en/blog/best-performing-assets-of-the-last-century/. In the 2008 Great Recession it outperformed major stock indices, and it proved the steadiest major source during the COVID-19 pandemic commodity.com/blog/gold-compared/.
More recently, gold's run has been dramatic—up ~27% in 2024 and ~65% in 2025, its best year since 1979 algoalpha.co/blog/gold-price-forecast-2026-2027. Yet it is more volatile than real estate: four negative years since 2011, worst being 2013 at −18.1%, and more year-over-year declines than stock indices from 2010–2020 commodity.com/blog/gold-compared/. Gold delivered double-digit annual returns in only 3 of the past 6 decades—a "feast or famine" profile awealthofcommonsense.com/2026/01/historical-returns-for-stocks-bonds-cash-housing-gold-2025/.
Where sources agree and disagree: Nearly all research agrees gold is a genuine crisis and high-inflation hedge. The disagreement is narrower: whether its recent surge represents a durable structural shift or a late-cycle mania. The data suggests the former, driven by forces beyond the inflation number itself (see below).
Inflation: Is the Fed Right That It's "Not a Big Deal"?
The debasement backdrop
The evidence is more nuanced than either camp admits. Historically, inflation was far higher and more painful in the 1940s, 1970s, and 1980s than today, and remains close to the ~3% long-run average awealthofcommonsense.com/2026/01/historical-returns-for-stocks-bonds-cash-housing-gold-2025/. Gold has proven a genuine inflation hedge in the periods that mattered—the 1970s in particular—but not a perfect one, with long stretches where it lagged productive assets over the full century vieclaire.com/en/blog/best-performing-assets-of-the-last-century/.
The debasement backdrop, however, is worth stating plainly: the U.S. dollar has lost roughly 95% of its purchasing power since the Federal Reserve's 1913 founding, which is the long-run case for holding a scarce, non-fiat asset at all silveroftruth.com/blog/dollarization-and-gold-2026-02-14. U.S. gross debt now exceeds $36 trillion, and gold has risen from ~$35/oz in 1971 to above $5,000 in real terms—a long arc of fiat erosion rather than year-to-year price stability usagold.com/gold-price-forecast-2026-market-outlook/.
The Fed's own pivot
On the current outlook, the Fed's own projections have moved in a way that undercuts the "not a big deal" framing. In March 2026, participants projected PCE inflation at 2.7% for 2026 (down from 6.0% in 2022), returning to 2.0% over the longer run federalreserve.gov/monetarypolicy/fomcprojtabl20260318.htm. By June 2026, the median PCE projection for 2026 had been revised up to 3.6%, with "Tariff Inflation" cited as a key driver federalreserve.gov/monetarypolicy/2026-07-mpr-part3.htm.
That revision has since hardened into action. By September 2026 the Fed (under Chair Kevin Warsh) delivered a 25 basis-point hike to a 3.75–4.00% funds rate, with Warsh explicitly stating inflation is "too high and has been for too long" spectrumlocalnews.com/us/snplus/business/2026/09/16/kevin-warsh-federal-reserve-interest-rate-decision. Core PCE sits at 3.2% and CPI at 2.4%, with August's headline reading at 3.4% year-over-year (a 0.4% monthly jump) chase.com/personal/investments/learning-and-insights/article/federal-reserve-raises-rates-officials-signal-one-more-hike-in-2026. Both the Fed and the White House attribute the pressure to an oil/energy supply shock tied to the U.S.-Iran conflict rather than demand overheating cnbc.com/2026/09/16/fed-meeting-today-live-updates.html. Bond yields climbed as a result—the 10-year Treasury hit 5%—pushing mortgage rates higher spectrumlocalnews.com/us/snplus/business/2026/09/16/kevin-warsh-federal-reserve-interest-rate-decision.
This is the crux for anyone holding a USD-based financial economy: the risk is not hypothetical—it is one the central bank itself revised upward and then responded to with tightening. That is precisely the environment in which gold's hedge case is most tested.
What's Driving Gold Today: A Structural Demand Revolution
Three factors govern gold today: real yields, central-bank flows, and crisis premiums convextrade.com/metrics/gold. Central-bank buying has been the dominant structural force—4,000+ tons cumulatively from 2022–2025, reinforced by BRICS-plus reserve diversification convextrade.com/metrics/gold. Central banks purchased a record 1,237 tonnes in 2025 at the fastest pace in 70 years and have bought 1,000+ tonnes for four consecutive years, roughly double the prior ~500-tonne annual norm gold.org/goldhub/research/central-bank-gold-reserves-survey-2026/.
The motivation is less about inflation than about sovereign safety: the 2022 freezing of Russian foreign assets demonstrated that reserve holdings can be weaponized, giving central banks an incentive to diversify into a non-sanctionable, non-liability asset gold.org/goldhub/research/central-bank-gold-reserves-survey-2026/. This "debasement thesis"—hedging